Florida is an at-will employment state, but at-will does not mean an employer can fire you for an illegal reason. Discrimination, unlawful retaliation, and certain other legally protected activities can still support an employment claim. An unfair termination is not automatically an illegal termination. The real question is why you were fired and whether the facts and evidence connect the decision to conduct prohibited by law. Timing and documentation can matter. A sudden change in discipline, performance reviews, scheduling, responsibilities, or treatment after a protected complaint or request may deserve closer review. Do not assume a probationary period means you have no legal rights. Company probation policies do not automatically eliminate protections against unlawful discrimination or retaliation. You may have heard someone say, “Florida is an at-will state, so your employer can fire you for any reason.” That is only partly true. At-will employment gives employers broad freedom to end an employment relationship, but it does not give an employer permission to violate state or federal employment laws. If you were fired for an unlawful reason, you may still have legal options. What Does At-Will Employment Mean in Florida? In most Florida jobs, employment is at will. This generally means an employer can end the employment relationship with or without advance notice, and an employee can usually leave the job at any time. An employer does not always have to give you a reason for terminating you. But the reason cannot violate applicable law. Depending on the employer, the facts, and the law involved, potentially unlawful reasons may include discrimination or retaliation connected to: Race or color. Religion. Sex or pregnancy. National origin. Age. Disability. Certain protected medical or family leave. Reporting discrimination or harassment. Reporting certain unlawful workplace conduct. Participating in certain investigations or other legally protected activity. The important question is often not simply whether you were fired. It is why you were fired, what happened before the decision, and what evidence supports the employer’s stated reason. One of the first things I tell employment clients is that unfair and illegal are not always the same thing. My job is to figure out which one we are dealing with. Can You Be Wrongfully Terminated During a Probationary Period? Yes. Being in a probationary period does not automatically eliminate your employment-law protections. You may hear that you have no rights during your first 30, 60, or 90 days. A probationary period is usually an employer’s policy; it is not a universal rule allowing an employer to disregard otherwise applicable employment laws. If an employee is terminated after two weeks for an unlawful discriminatory or retaliatory reason, the fact that the employee was still within a probationary period does not necessarily make the termination lawful. Length of employment can matter for particular claims, benefits, or leave protections. That is different from saying there is a blanket period during which employment laws do not apply. What Does Wrongful Termination Look Like? Wrongful termination can take many forms. Depending on the facts and applicable law, a potential claim may deserve review if you: Reported workplace harassment and were fired shortly afterward. Complained about discrimination and then experienced a sudden change in discipline or performance reviews. Requested or used legally protected leave and lost your job. Participated in an investigation involving alleged unlawful workplace conduct. Reported certain unsafe or unlawful workplace practices and were punished. Were treated differently from similarly situated employees because of a legally protected characteristic. Timing can matter. If you have years of positive performance reviews and are suddenly disciplined immediately after making a protected complaint, that change may deserve closer review. But timing alone does not prove the reason for a termination. An unfair termination is also not automatically an illegal one. The facts, the employer’s explanation, comparable employees, and the available evidence all matter. Why Documentation Matters in a Florida Wrongful Termination Case If something seems wrong at work, start keeping accurate records. Document important events in writing whenever possible and preserve records you are legally entitled to keep. Potentially useful records may include: Emails and workplace messages. Performance reviews. Disciplinary notices. Written complaints you submitted. Responses from supervisors or human resources. Employee handbooks and workplace policies. Relevant schedules or time records. You should also create a timeline showing important dates, conversations, complaints, requests, and employment decisions while the details are still fresh. I tell clients: before we decide what the employer did wrong, let’s build the timeline. What happened before the complaint? What changed afterward? Who said what? What do the documents show? Keep your writing factual. Record what happened, when it happened, who was involved, and what was said. If you receive an inaccurate accusation or disciplinary notice in writing, consider responding accurately and professionally in writing. A contemporaneous record can become important if the explanation for your termination later changes. Can Your Employer Retaliate Against You for Making a Complaint? Employers generally cannot lawfully retaliate against an employee for engaging in activity protected by an applicable employment law. Whether a particular complaint or action is legally protected depends on the facts and the law involved. Retaliation does not always mean immediate termination. Depending on the circumstances, adverse treatment may include: Demotion. Reduced hours. Loss of responsibilities. Unfavorable schedule changes. Unusual or escalating discipline. Negative performance reviews. Exclusion from opportunities. Termination. If negative treatment begins after you report discrimination, harassment, request protected leave, participate in a protected investigation, or engage in another potentially protected activity, document what changed and when. What Can You Recover in a Wrongful Termination Claim? The compensation and other remedies available depend on the type of claim, the law involved, and the facts that can be proven. Depending on the claim, potential remedies may include: Lost wages. Lost employment benefits. Future lost income or front pay in appropriate cases. Compensation for emotional distress when available. Attorneys’ fees and legal costs when authorized by law. Reinstatement in appropriate cases. Punitive damages when legally available and supported by the facts. You should not assume that every wrongful termination case results in a large financial settlement. The value and available remedies depend on what happened, what you lost, the law that applies, and what the evidence can prove. Can You Get Your Job Back After Wrongful Termination? In some cases, reinstatement may be available or may become part of settlement discussions. You may still like your job or want to return because of your salary, benefits, seniority, career path, or other reasons. In other situations, returning may not be realistic or desirable. The appropriate resolution is case-specific. An employment attorney can help evaluate whether reinstatement, compensation, a negotiated separation, or another resolution makes sense under the circumstances. What Should You Do If You Think You Were Wrongfully Fired? Start by preserving evidence. Save relevant emails, messages, employment records, performance reviews, disciplinary documents, complaints, and workplace policies that you are legally permitted to retain. Write down a timeline while the details are still fresh. Be cautious before signing a severance agreement, release, resignation, or other document that may affect your rights. If you are unsure what a document means, have it reviewed before signing. Then speak with a Florida employment attorney who can evaluate the events leading to the termination, any complaints or requests you made, how the employer responded, whether comparable employees were treated differently, and what documentation supports the competing explanations. Sometimes a termination is unfair but lawful. Other times, facts that initially seem minor can become important evidence of discrimination, retaliation, interference with protected rights, or another employment-law violation. Sometimes I have to tell a client, “I understand why you’re upset, but that does not necessarily make it illegal.” Other times, once we put the timeline and documents together, the picture looks very different. Speak With a Florida Wrongful Termination Attorney Losing your job can affect your income, health insurance, career, and financial stability. You should not assume that at-will employment means you have no rights. If you believe you were fired because of discrimination, retaliation, protected leave, or another unlawful reason, Hilliman Legal Solutions can review what happened and explain your options. Speaking with an attorney early can also help you identify applicable deadlines, preserve evidence, and understand the effect of severance agreements, releases, or other documents before you sign them. Think You Were Wrongfully Terminated? At-will employment does not answer every termination question. The reason for the decision, the timing, the employer’s explanation, and the available evidence all matter. Learn more about our Employment Matters practice or call Hilliman Legal Solutions at (855) 994-4805 to schedule a consultation. _____________________________________________________________________________________________________________________________ Frequently Asked Questions 1. Can you sue for wrongful termination in Florida? You may have a claim if the termination violated an applicable state or federal law. Potential examples can include unlawful discrimination, retaliation, interference with certain protected rights, or termination connected to other legally protected workplace activity. Whether a claim exists depends on the facts and the law that applies. 2. Is being fired without warning illegal in Florida? Not necessarily. At-will employment generally does not require an employer to provide advance notice before terminating an employee. A termination may still be unlawful if the reason violates an applicable employment law or protected right. 3. What evidence helps prove wrongful termination? Useful evidence can include emails, text messages, performance reviews, disciplinary notices, complaints to human resources, workplace policies, witness information, schedules, and a written timeline. Evidence showing how the employer treated you before and after protected activity, as well as how similarly situated employees were treated, may also be important.
If you are hit by a semi-truck, tractor-trailer, delivery truck, or other commercial vehicle, your case may look like a car accident at first. In reality, truck accident claims are often much more complicated.
Construction projects require a significant investment. When work is not performed properly, the financial consequences can be serious. Defective construction can lead to costly repairs, project delays, safety hazards, reduced property value, and legal disputes.
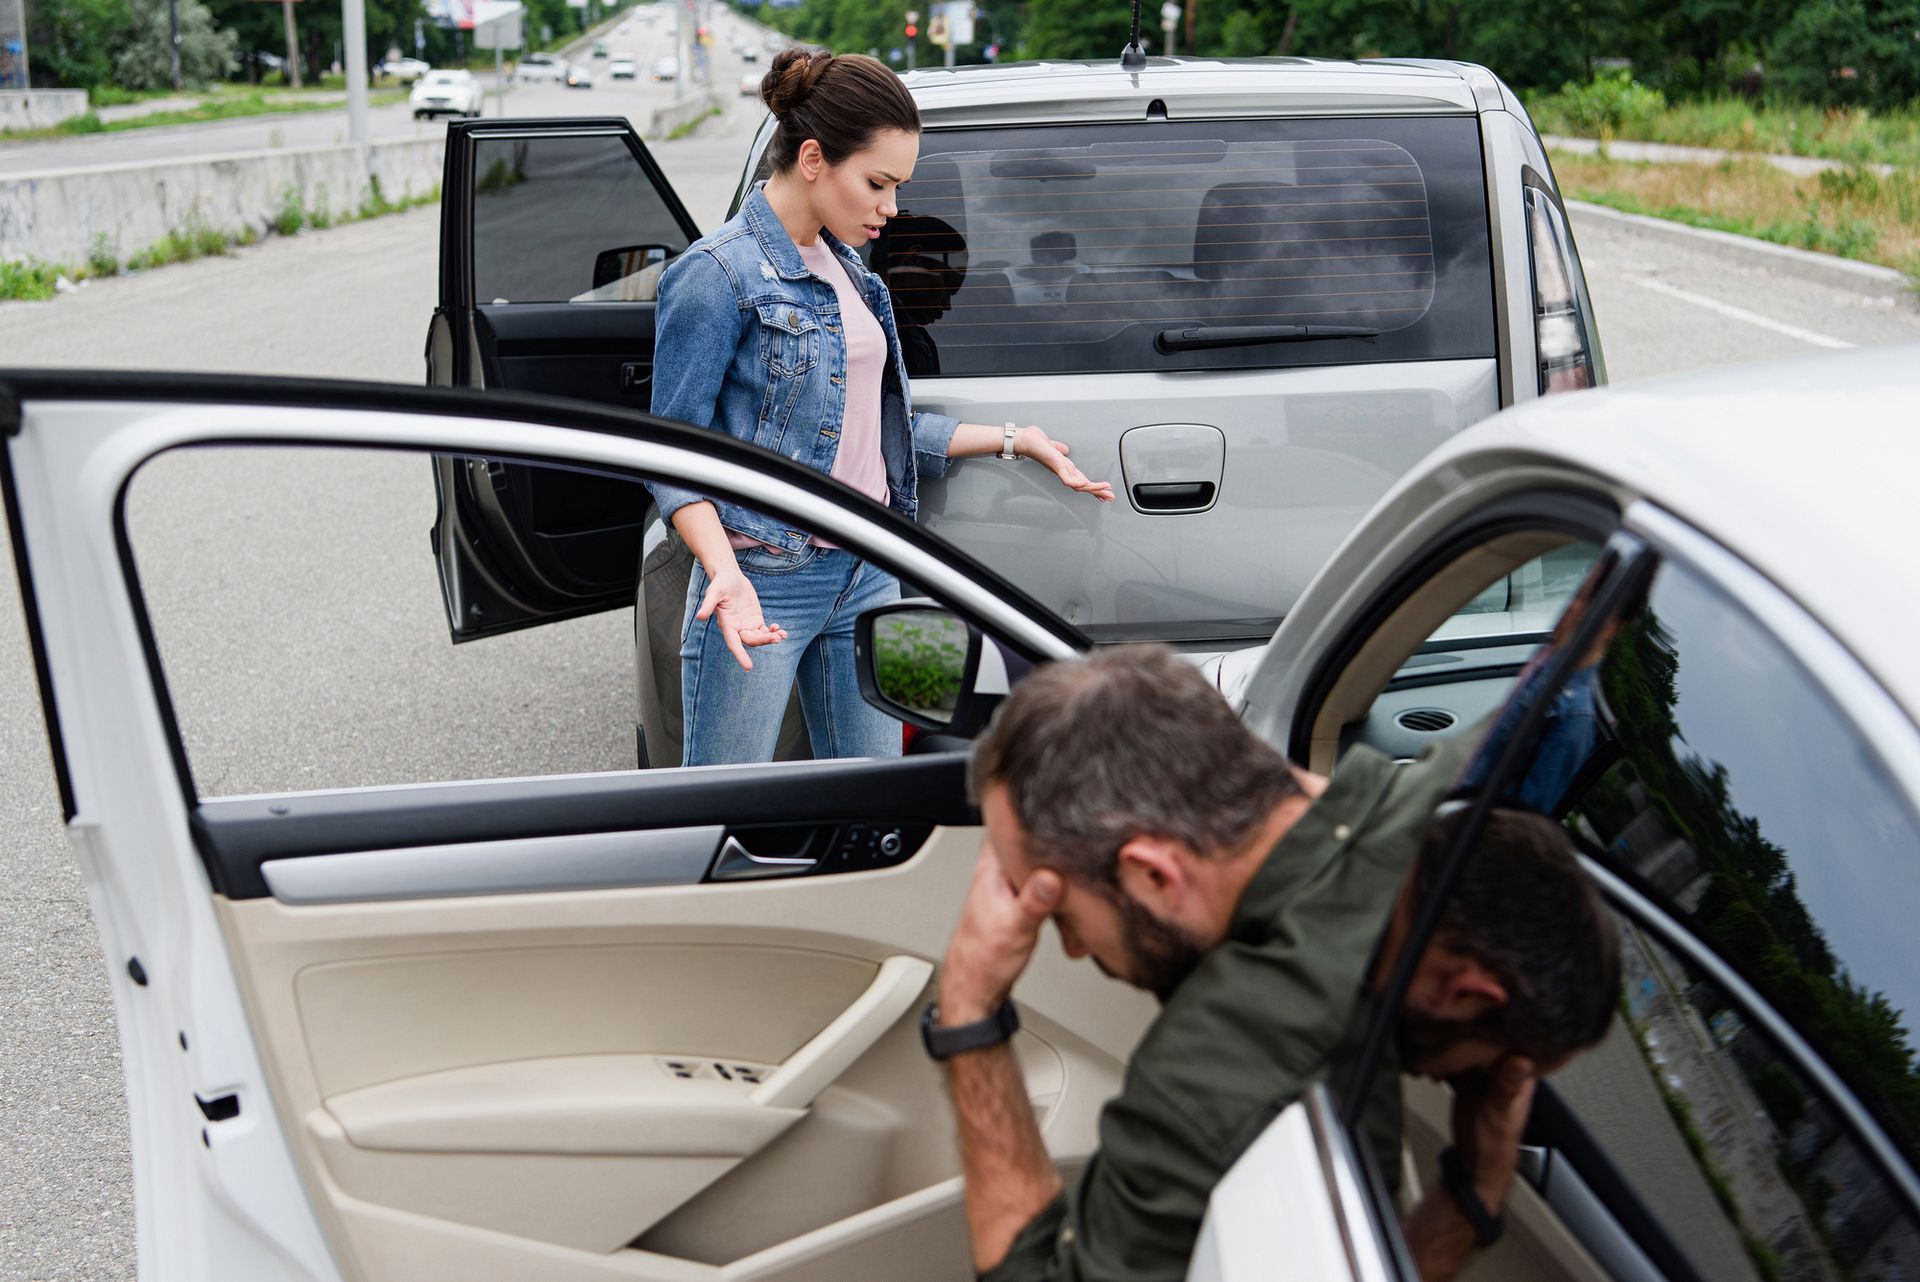
If you are involved in a car accident that was not your fault, your actions immediately afterward can affect both your health and your financial recovery. You should prioritize safety, document the accident, seek medical care, notify your insurance company, and consider speaking with an attorney as soon as possible…